

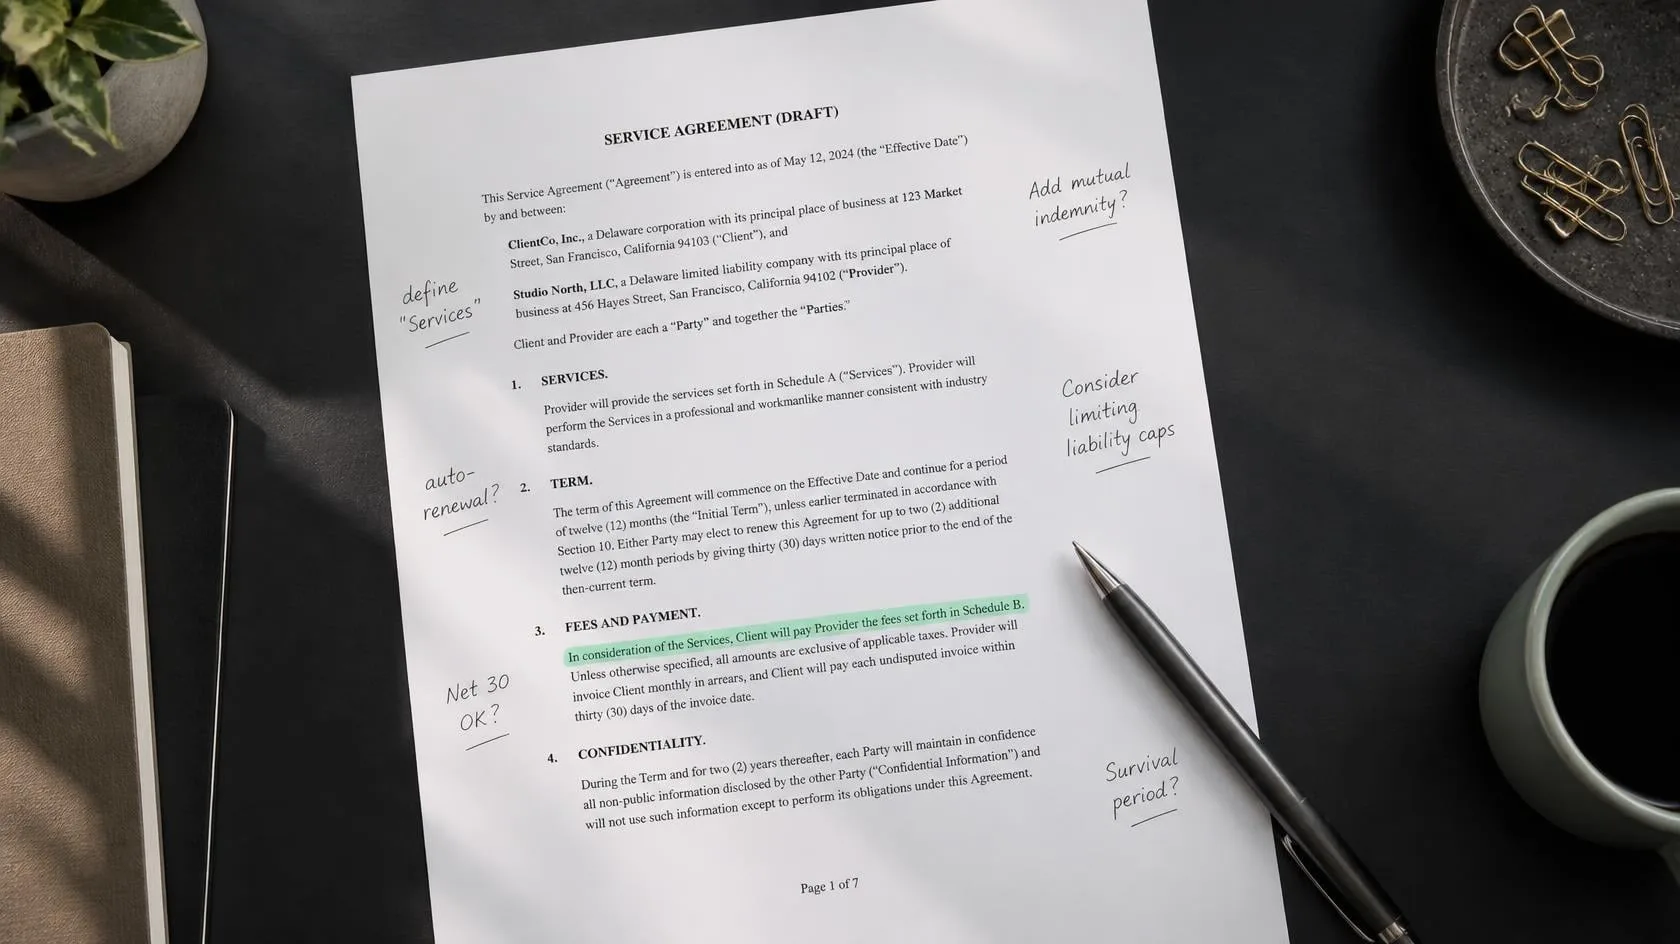
At a glance
- A shareholders’ agreement is not compulsory for a Finnish private limited company (Oy), but it can define ownership arrangements that legislation and the articles of association do not settle.
- The agreement normally binds its parties. The company may also be a party if it is properly represented, but mandatory company law still prevails.
- Transfer terms, reserved matters, founder departures, valuation and deadlock procedures should work together rather than appear as isolated clauses.
- A contractual transfer restriction is not the same as a redemption or consent clause in the articles of association.
- Define confidentiality and dispute procedures expressly, and choose contractual remedies that fit the risks.
A shareholders’ agreement can turn broad expectations between founders into workable rules: who contributes money or time, which decisions need wider support, what happens when someone leaves and how an eventual sale is handled. It is most useful when drafted before the parties’ interests diverge.
This guide concerns shareholders’ agreements for Finnish private limited companies. If the company has not yet been incorporated, start with the guide to company formation in Finland. Tax, employment, intellectual-property and regulatory questions may require separate analysis.
What does a shareholders’ agreement do?
A shareholders’ agreement is a contract. It complements the Finnish Limited Liability Companies Act and the company’s articles of association, but it does not replace either. It can regulate how its parties exercise voting rights, fund the company, transfer shares and deal with founder departures.
The agreement normally binds the parties that have accepted it. A new shareholder does not automatically become a party simply by acquiring shares, so transfer documents commonly require a deed of adherence or another agreed accession mechanism. The company itself can be a party if the agreement is approved and signed with proper authority. Even then, the agreement cannot authorise an unlawful distribution of assets or require a company organ to disregard mandatory law.
A breach of the agreement does not normally make a shareholders’ meeting or board decision invalid merely because the decision conflicts with the agreement. The breach may lead to contractual remedies between the parties. A decision can still be challengeable on separate grounds under the Limited Liability Companies Act or the articles of association.
Shareholders’ agreement or articles of association?
The articles of association are registered and publicly available. They form part of the company-law framework and apply to shareholders according to that framework, including later owners. A shareholders’ agreement is not filed with the Finnish Trade Register. That does not make it inherently secret: include an appropriate confidentiality clause and consider necessary disclosures to investors, lenders, authorities and professional advisers.
Finnish law tightly limits transfer restrictions that may be included in the articles. Under Chapter 3, sections 6–8 of the Limited Liability Companies Act, the permitted mechanisms are a redemption clause and a consent clause. A redemption clause operates when a share has transferred and gives the specified person a right to redeem it under the clause. A consent clause can make an acquisition by transfer subject to company consent.
A contractual right of first refusal or obligation to offer shares before a sale is different. It can bind the contracting shareholder, but it does not by itself give the same company-law effect against an incoming owner. Conversely, not every governance, employment or leaver provision belongs in the articles. The two documents should be coordinated clause by clause.
Key terms to address
Parties, ownership and accession
Identify the company, each shareholder, their share classes and any relevant holding companies. State whether the company is a party and which obligations apply to it. Set a practical accession process for future shareholders.
Governance and reserved matters
List decisions that require specified support, such as a share issue, material borrowing, a major acquisition or a sale. Use thresholds that fit the ownership structure and distinguish shareholders’ decisions from board matters.
A shareholder may have a right to nominate or support a board candidate. Once appointed, however, a director owes duties to the company and must promote its interests, not simply follow the appointing founder’s instructions.
Funding, work and intellectual property
Explain whether future funding is expected as equity, shareholder loans or third-party finance, who decides on it and what happens if a shareholder does not participate.
If founders work in the business, define their commitment and coordinate the agreement with their employment, managing-director or consultancy arrangements. It is not a substitute for an employment contract. Ensure that the company receives the intellectual-property rights it needs.
Transfers, tag-along and drag-along rights
Transfer clauses may cover permitted transfers, first-offer procedures, valuation and accession by the buyer. A tag-along right can let minority shareholders participate in a sale on corresponding terms. A drag-along right can enable an agreed majority to require a whole-company sale.
Define the trigger, price, notices, warranties and completion mechanics. Check the clauses against the articles of association so that the procedures are consistent.
Vesting and founder departures
Founder vesting is often implemented through transfer, call-option or leaver arrangements rather than shares reverting automatically. A four-year schedule with a one-year cliff is only one commercial example, not a rule of Finnish law.
Define what counts as leaving, who may acquire the shares, the price and how good-leaver and bad-leaver situations differ. Do not assume that a company sale automatically accelerates vesting. Any acquisition or redemption by the company must comply with mandatory company-law rules, including decision-making, available-funds and solvency requirements. The tax consequences also need checking.
Profit, valuation and exit
The parties can record their intended dividend policy, but cannot contract out of statutory distribution requirements. For exits, define the valuation date, method, treatment of debt and cash, expert procedure and cost instead of relying on unexplained “fair value”.
Confidentiality, non-compete and non-solicitation
Specify what is confidential, permitted disclosures and the duration of protection. A non-compete should protect a legitimate interest and be proportionate. Share ownership alone does not make every restraint enforceable, and employment-law restrictions may apply to an employee-shareholder.
Plan for deadlock
A 50:50 company does not have a bespoke statutory tie-breaker for every commercial disagreement, but not every disagreement blocks all action. Identify genuine deadlock decisions and use a staged response, perhaps escalation followed by mediation.
A buy–sell mechanism, option or sale process may suit some companies, but can favour the party with better access to finance. Its triggers, valuation and funding need careful design.
Remedies and dispute resolution
A contractual penalty can create a pre-agreed consequence for defined breaches, but it is not the only remedy. Explain its relationship with damages, performance obligations, termination and interim relief. Under section 36 of the Finnish Contracts Act, an unreasonable term or its application may be adjusted or disregarded.
Choose litigation or arbitration proportionately. Arbitration can offer a private process, but it can be expensive. Privacy does not itself guarantee party confidentiality, so address confidentiality expressly and select the seat, language, rules and number of arbitrators.
Can you use a template?
A reliable template may contain detailed terms. The question is whether it fits the company’s ownership, founder contributions, planned investment, share classes, intellectual property and intended exit.
Review its definitions and cross-references, remove unselected alternatives and test realistic scenarios: a founder leaves, declines a funding round or receives an outside offer. Coordinate amendments with the articles, employment documents and financing arrangements.
When should the agreement be made or updated?
The best time is usually at formation or before shares are issued to several founders. Review it when an investor or key employee becomes an owner, the company raises finance, creates a share class or prepares for sale. Agreement becomes harder after a dispute begins.
Checklist before signing
- Confirm the parties, cap table, share rights, authority to sign and accession process.
- Map reserved matters, board arrangements, information rights and genuine deadlock risks.
- Align transfer, tag-along, drag-along, vesting, leaver and valuation provisions.
- Check funding, work, intellectual property, confidentiality and proportionate restrictions.
- Coordinate the agreement with the articles of association and select workable remedies and dispute procedures.
When tailored legal help is useful
Review is particularly useful where founders contribute different assets, an investor is joining, ownership is split equally, more than one jurisdiction is involved, or leaver and exit provisions may transfer valuable shares. I assist with Finnish shareholders’ agreements and related articles-of-association questions. We will agree on the scope, fee and timetable before work begins.
Frequently asked questions
Is a shareholders’ agreement mandatory in Finland?
No. A Finnish private limited company can operate without one. The agreement is used to add contractual rules on matters such as governance, founder commitment, share transfers and exits. The memorandum of association and articles required for incorporation are separate documents.
Does a shareholders’ agreement bind a new shareholder?
Not automatically merely because the person acquires shares. The transfer documents should require the new owner to join the agreement, usually through an accession document. Provisions in the registered articles may apply independently, but Finnish law permits only specified types of share-transfer restriction in the articles.
Can the company itself be a party?
Yes, if the company enters the agreement through proper corporate authority and representation. Its participation can be useful for information or administrative obligations, but it cannot override mandatory company law, lawful distribution requirements or directors’ duties to the company.
Can the agreement stop a shareholder from selling?
It can impose contractual sale procedures and consequences on a shareholder who is a party. That is different from a transfer restriction in the articles of association. Coordinate contractual pre-emption or first-offer rights with any statutory redemption or consent clause intended for the articles.
What happens if someone breaches the agreement?
The available response depends on the clause and applicable law. It may include a contractual penalty, damages, an order to perform or refrain from an act, termination rights or interim measures. A corporate decision is not normally invalid solely because it breached the agreement, although separate grounds under company law or the articles may affect that decision.
Sources
- Limited Liability Companies Act (624/2006), current Finnish text (in Finnish) – including general principles, directors’ duties, articles of association and the permitted redemption and consent clauses.
- Limited Liability Companies Act, English translation incorporating amendments up to 660/2022 (PDF) – useful for terminology; check the current Finnish text for later amendments.
- Contracts Act (228/1929), current Finnish text (in Finnish) – section 36 on adjustment of unreasonable contract terms.
- Suomi.fi: memorandum of association and articles of association of a limited liability company – official company-formation guidance on the statutory incorporation documents.
Last updated: 28 September 2026
